Market overview and structural significance of the Porous Plastic Products Market
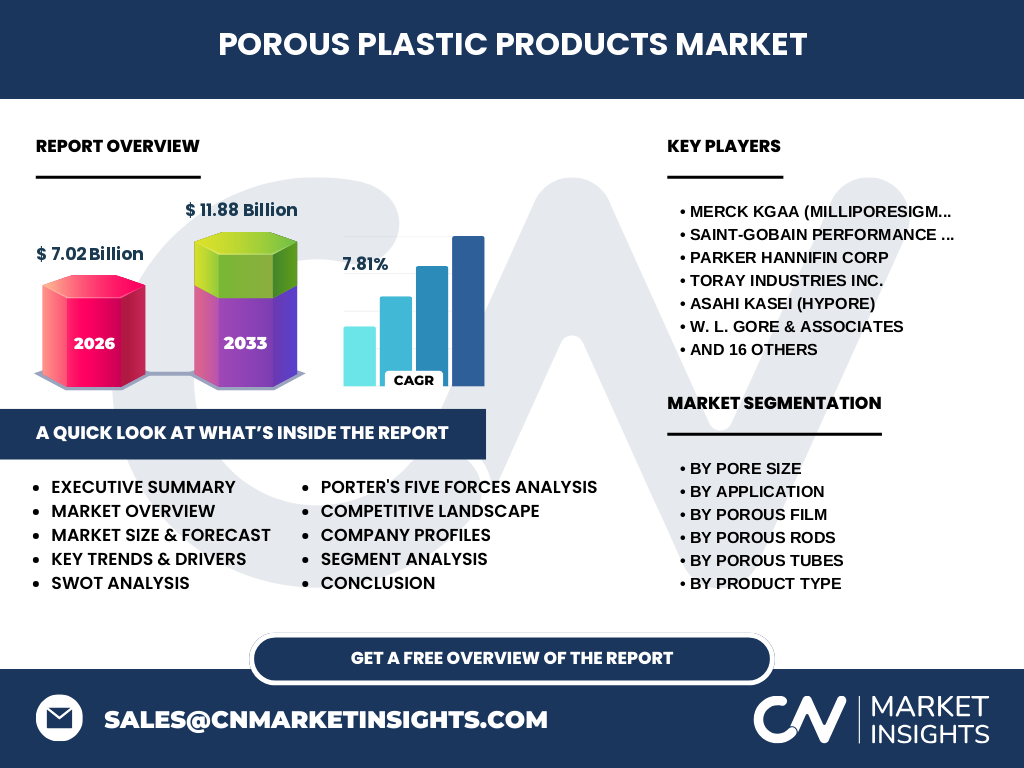
The Porous Plastic Products Market encompasses specialized engineered polymers designed with controlled permeability, reaching a valuation of 7.02 Billion by 2026. These materials utilize raw inputs like polypropylene and polytetrafluoroethylene to enable precise filtration, fluid flow control, and gas separation across demanding industrial environments.
Structural Growth Drivers and Market Restraints
Our analysis indicates that stringent environmental mandates by regulatory bodies like the EPA and FDA serve as primary catalysts, driving demand for advanced filtration. However, the market faces notable supply chain bottlenecks involving the procurement of specialized fluoropolymer precursors and strict compliance hurdles in medical-grade manufacturing.
Emerging Trends and Technological Shifts
The industry is experiencing a rapid pivot toward nano-porous and composite porous films tailored for high-efficiency electronics and electric vehicle battery separators. Innovators are increasingly leveraging advanced sintering and track-etching techniques to achieve tighter pore size distribution tolerances.
COVID-19 Impact Analysis and Market Resilience
The pandemic dramatically accelerated demand for medical-grade porous sheets and ventilator components, stretching supply chains across major manufacturing hubs in Shenzhen and Rotterdam. Post-COVID recovery trajectories reflect heightened inventory buffering and localized sourcing strategies among leading healthcare OEMs.
Competitive Benchmarking and Market Concentration
The landscape is characterized by moderate concentration, featuring dominant multinational players such as Merck KGaA (MilliporeSigma), Saint-Gobain Performance Plastics, and W. L. Gore & Associates. These industry leaders maintain a competitive moat through proprietary membrane technologies and extensive patent portfolios in expanded polytetrafluoroethylene.
Executive Summary of the Porous Plastic Products Market Industry Trends
Driven by robust demand in water treatment and semiconductor manufacturing, the Porous Plastic Products Market is poised for accelerated expansion. Based on our research, the sector will surge from 7.02 Billion in 2026 to reach 11.88 Billion by 2033, expanding at a notable CAGR of 7.81%.
Market Forecast Projections Through 2033
The data suggests sustained, upward momentum as global capital expenditure shifts toward advanced liquid filtration and gas separation infrastructure. The market will capture incremental revenue growth, scaling from its 2026 baseline to 11.88 Billion by 2033, underpinned by a consistent 7.81% CAGR.
Comprehensive Segmentation Breakdown
Market segmentation covers distinct structural and functional categories essential for targeted deployment.
- By Product Type: Porous Film, Porous Membranes, Porous Sheets, Porous Tubes, Porous Rods, and Other Product Types.
- By Material Type: Polypropylene, Polyethylene, Polytetrafluoroethylene, Polyvinylidene Fluoride, Polyamide, Polyurethane, and Others.
- By Pore Size: Microporous, Mesoporous, and Macroporous.
Regional Market Distribution and Performance Dynamics
Geographic performance is heavily skewed toward regions with dense chemical processing and semiconductor fabrication clusters. North America and Europe dominate consumption due to strict environmental compliance, while Asia-Pacific represents the fastest-growing frontier driven by expanding water treatment infrastructure in China and India.
In-Depth Regional Review of High-Growth Zones
In Asia-Pacific, rapid industrialization and government-backed desalination initiatives create strong demand for microfiltration membranes and filtration porous tubes. Meanwhile, North American growth is anchored by stringent USP Class VI medical standards, favoring specialized domestic producers like Porex Corporation and Parker Hannifin Corp.
Strategic Positioning of Leading Company Profiles
Key market participants deploy distinct differentiation strategies to capture high-margin segments. Firms like Pall Corporation and Donaldson Company Inc. focus heavily on proprietary industrial filtration modules, whereas Asahi Kasei (Hypore) and Toray Industries Inc. prioritize ultra-thin separator films for lithium-ion battery applications.
Porter's Five Forces Analysis of Competitive Pressures
Industry rivalry remains intense among established tier-one suppliers possessing proprietary sintering patents. Supplier power is moderate, moderated by alternative raw material inputs like polyethylene and polypropylene, while threat of substitution is low given the specialized performance requirements of porous membranes in extreme chemical environments.
SWOT Analysis of the Porous Plastic Products Market
Strengths lie in versatile polymer chemistry and tailored pore size distribution capabilities. Weaknesses involve high initial tooling costs for custom engineered components. Opportunities abound in green hydrogen production setups, while primary threats stem from volatile petrochemical feedstock prices and geopolitical trade restrictions.
Value Chain Analysis from Raw Materials to End-Users
The value flow originates with petrochemical refiners supplying virgin polymer resins, which are subsequently converted via extrusion, phase inversion, or sintering by specialized compounders. These intermediate porous films and tubes are integrated by OEMs into end-use systems for water treatment, automotive ventilation, and biopharmaceutical processing.
Strategic Investment Insights and High-Potential Opportunity Areas
Investors should target manufacturers specializing in composite porous films and biomedical porous rods, as these sub-segments benefit from high switching costs and robust healthcare sector demand. Companies partnering with semiconductor fabrication hubs will capture superior long-term yield potential.
Conclusion and Strategic Takeaways for Industry Stakeholders
The Porous Plastic Products Market analysis confirms a highly lucrative, innovation-driven sector underpinned by a 7.81% CAGR through 2033. Success requires continuous investment in sustainable polymer recycling capabilities and tight adherence to evolving global medical and environmental compliance standards.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registry data from major maritime ports, primary stakeholder interviews with chief technology officers, and secondary macroeconomic indicators from chemical manufacturing associations to ensure uncompromising market sizing accuracy.
Scope of the Report and Analytical Limitations
This report covers global revenue performance, volume shipments, and technology adoption trends across six core regions from 2026 to 2033. Limitations include inherent forecasting uncertainties regarding sudden geopolitical trade tariff alterations and unforeseen disruptions in global fluoropolymer raw material supply chains.
Recent Industry Developments and Strategic Corporate Moves
Recent market activity highlights aggressive capacity expansions and strategic acquisitions among tier-one players. For instance, companies like Entegris Inc. and Sartorius AG have announced targeted joint ventures to scale up manufacturing of ultrafiltration membranes for advanced bioprocessing applications in European and North American facilities.